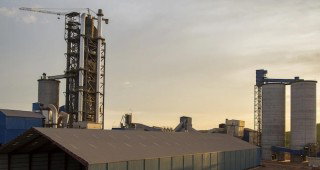
Indian cement producers are expected to invest approximately INR750bn (US$8bn) across FY2026–27 and FY2027–28, despite higher fuel costs putting pressure on profitability, according to Crisil Ratings.
In its analysis published on 18 November, the agency forecasts 110–120Mta of capacity additions over the two financial years. Around two-thirds would comprise split grinding units, allowing producers to use existing clinker capacity and locate cement production closer to customers.
Crisil expects capacity utilisation to remain around 70 per cent as additions broadly match incremental demand. Its analysis covers 18 producers representing approximately 90 per cent of India’s installed cement capacity.
Operating profitability is forecast to decline to INR875–900/t in FY2026–27, from approximately INR980/t a year earlier. Power and fuel costs have increased by INR100–125/t, with price rises expected to offset only part of the pressure.
Higher investment and weaker profitability are expected to lift net debt/EBITDA to approximately 1.5 times this financial year, its highest level in five years. Crisil forecasts leverage easing to 1.2–1.3 times in FY2027–28 as profitability and cash generation recover.
Handpicked stories, in your inbox
Our editors pick the top news delivered to your inbox. Sign-up today!