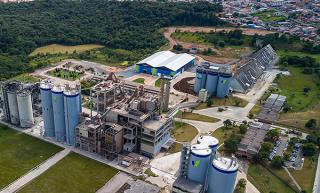
Lafarge’s turnover improved 1.8 per cent to €16,169m in 2010, with cement turnover being 1.7 per cent higher at €10,280m. Cement deliveries from the 168 plants were 3.9 per cent lower at 135.7Mt. Weaker European and North American markets led to a further 1.4 per cent reduction in aggregates deliveries from the 579 production sites to 193.2Mt, while ready-mixed concrete shipments from the 1139 batching plants fell by 8.4 per cent to 34Mm³. Lafarge is the market leader in cement in France, Great Britain, Greece, Austria, North America and in a number of developing markets, with a particularly strong positions in Arab-speaking countries.
Lafarge’s 2010 EBITDA edged ahead by 0.4 per cent to €3614m while the running profit before tax declined 1.9 per cent to €1541m after a net interest charge that was down by 4.5 per cent. Thanks to lower exceptional charges, helped by the capital gain on the Cimpor stake, the pre-tax profit rose by 9.5 per cent to €1430m. That included a €154m gain from the sale of emission rights. Net debt, at the end of December stood at €13,993m to give a gearing level of 76.8 per cent, compared with 82.1 per cent a year earlier.
Capital investment was reduced by a further 18.5 per cent to €1309m, while spending on acquisitions, ignoring the asset swap with Votorantim, amounted to just €84m. Capital investment in 2011 is expected to be around €1000m.
Subscribe to get access to all News, Articles and Video sections of the CemNet.com website.
SubscribeHandpicked stories, in your inbox
Our editors pick the top news delivered to your inbox. Sign-up today!