SCCC is expensive trading at PE of 15.4x, compared to the cement sector’s average of 13.1x. Limited growth for the company is expected as there is no plan for any major investments and the utilization rate of its cement unit is stretched. The stock is overpriced and trading above DCF target price of Bt256. Underperform is maintained.
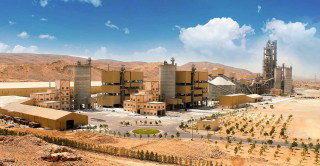
JK Cement opens construction chemicals plant in UAE
JK Cement subsidiary, JK DryChem Industries LLC, has opened a new construction chemicals manufac...