New strikes on vessels in the Strait of Hormuz (SoH) and US military action against Iran have been immediately reflected in oil prices. This has dragged gas prices higher through a combination of very low European gas storage and damage to the refineries in Qatar. The OECD has warned that a long-lasting conflict could reduce growth in the area from 1.7 to 0.5 per cent and see energy demand fall. Power prices in Europe have surged, adding to inflationary pressure. Eurozone inflation reached 3.3 per cent in August, while the USA reached 3.4 per cent in July, increasing expectation that both the European Central Bank and the US Federal Reserve will increase interest rates at upcoming meetings. Agricultural commodity prices are also at their highest levels since 2022, driving further inflation. The USA is trying to reopen peace talks between Ukraine and Russia, after strikes on Russian facilities added to a bullish oil scenario.
The VIX volatility index remained low at 15.5 (no “fear”), below the critical level of 20. There was little movement in the currency markets. The euro rose 0.5 per cent against the dollar to US$1.160. Brannvoll ApS forecasts a range of US$1.10-1.25 in 2026, with an average of US$1.19.
| PRICES AT A GLANCE - 4 September 2026 | ||
| Brent crude oil – bbl | US$96.00 | |
| Coal API 2 | 4Q26 | US$136.00 |
| Cal 2027 | US$134.00 | |
| Coal API 4 | 4Q26 | US$124.00 |
| Cal 2027 | US$123.00 | |
| Petcoke USGC 4.5 per cent S 40HGI | FOB | US$91.00 |
| CFR ARA | US$122.00 | |
| Petcoke USGC 6.5 per cent S 40HGI | FOB | US$86.00 |
| CFR ARA | US$117.00 | |
Oil
Renewed hostilities between the USA and Iran have disrupted traffic through the SoH and fuelled an oil market rally, while Russian oil exports have also diminished.
At its latest meeting, OPEC+ agreed to add supply to the market, although short-term oil rallied to just below US$100. A prolonged closure to the SoH could return prices to US$115. The USA has struck a deal that sees it take control of 20 per cent of Venezuelan oil, although US companies must spend heavily to set up the production and export. A potential stand-off is looming as China claims it is owed oil from Venezuela as a guarantee for large loans.
The oil markets are still in sharp backwardation with Dec 27 forward rates ahead at US$20 lower front month Oct 26. Brent oil has risen 13 per cent month on month (MoM) to US$96.00 and if spikes occur a price of US$115 could easily be seen. The TTF gas prices have risen to EUR73 in the front month and the (Cal27) gas price is substantially higher, seen at EUR55. Brannvoll ApS forecasts a Brent trading range of US$55-125 and average of US$75 for 2026 (the upper end was raised by US$40 due to the Middle East conflict).
Coal
Coal prices rallied unexpectedly as higher gas prices boosted demand, while absent Russian exports, lower Colombian exports and rail problems in South Africa constrained supply. Chinese domestic production has decreased due to mine inspections and in turn pushed up the Australian coal prices. India also saw increased demand, while very low water levels on the Rhine have made transport difficult.
The API2 4Q26/front quarter (FQ) contract rose 15 per cent MoM to US$136, for a new range of US$120-155. The Cal27 contract rose 14 per cent to US$134. API4 FQ contracts were up 16 per cent at US$124, entering a new short-term range of US$115-135. Brannvoll Aps forecasts a API2 FQ contract range of US$85-130, averaging at US$100, and API4 in a range of US$80-125 in 2026.
Petcoke
Rising prices across the energy complex directly impacted the petcoke market. Surging coal prices have increased the discount for petcoke but left room for further price increases. Notably, US refineries are processing greater volumes of heavy Venezuelan crude, producing petcoke with a sulphur content of 4.5 per cent and narrowing its price differential with 6.5 per cent sulphur petcoke. Indian buyers returned after the monsoon, as did Chinese traders with no active enforcement of the Chinese three per cent sulphur ban. Normal exports from Saudi Arabia and Oman have been halted, adding to the price pressure. Turkish cement producers have been active in the market as the cessation of Russian coal supplies means petcoke still offers a good discount.
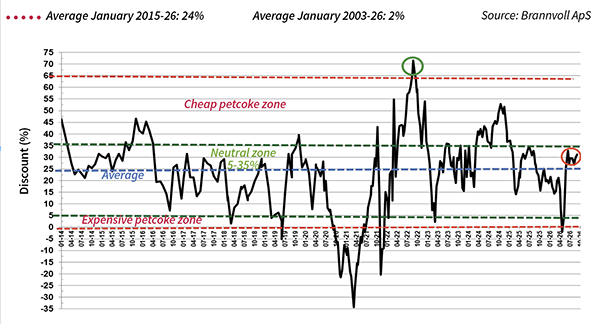
The USGC FOB 6.5 per cent contract is up eight per cent MoM to US$86, while the API4 discount rose five per cent to 45 per cent. The USGC ARA 6.5 per cent contract again rose by eight per cent MoM to US$117 and the discount increased to 31 per cent. The USGC FOB 4.5 per cent contract rose seven per cent MoM to US$91, with the FOB discount to API4 up to 41 per cent. The USGC ARA 4.5 per cent contract rose eight per cent to US$122, with the discount rising to 27 per cent. Brannvoll ApS forecast a range of US$85-105 (short-term up to 120) for the ARA 6.5 per cent contract in 2026, with an average of US$95 and a discount of 25 per cent.
By Frank O. Brannvoll, Brannvoll ApS, Denmark
Handpicked stories, in your inbox
Our editors pick the top news delivered to your inbox. Sign-up today!