The EUA market is still awaiting the end of Brussels summer holidays to see the implementation of the EU ETS process. The reform was mentioned in the last issue and has mostly been interpretated as positive in the short term but negative in the long term. The revision includes extending the CBAM period and free allocation from 2024 until 2028. It is important to have this ready in CBAM models as the mechanism is likely to be implemented next year.
The carbon market is being driven by the energy complex as it responds to geopolitics and the situation in the Strait of Hormuz. The fighting has pushed oil higher, but the reduction in exports of LNG and gas has moved gas higher and made coal-fired power generation the cheapest solution. Increased coal use has boosted demand for EUAs to cover higher emissions, also encouraging speculators to take long positions. The European Commission’s DG TAXUD plans to revise CBAM default values for several countries. This work is underway, with progress also hoped for on verifier accreditation, allowing importers to use verified actual emissions rather than default values.
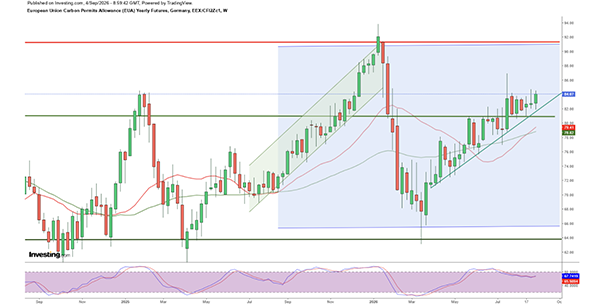
The Dec 2026 contract increased two per cent at EUR84.00 and a range of EUR81-86 is expected over the next month. The long-term EUA price for 2030 was up by four per cent to EUR98.50. The UK Allowance (UKA) December 2026 contract rose by just one per cent to GBP60 (EUR71) as the EU process is not directly involving the UK market (yet). Brannvoll ApS widens its forecast to a range of EUR60-95 in 2026 with an average of EUR80 for the Dec 26 contract.
By Frank O. Brannvoll, Brannvoll ApS, Denmark
Handpicked stories, in your inbox
Our editors pick the top news delivered to your inbox. Sign-up today!